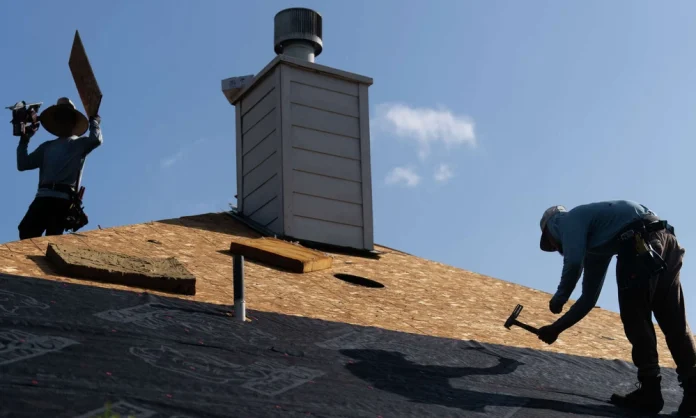


Drive roughly fifty miles from a cul-de-sac in Cypress to a bayside street in Seabrook and the houses start to look familiar. Brick fronts, two-car garages, architectural shingles in weathered wood and charcoal. Up close, though, the roofs over those homes are often built to different rules, checked by different inspectors and judged by different insurers. Most homeowners only discover this when a storm forces a replacement.
The dividing line is State Highway 146. Harris County homes east of it, in La Porte, Seabrook, Shoreacres, Morgan’s Point and parts of Pasadena, sit inside the state’s designated catastrophe area along with fourteen coastal counties. Everything west of that line, from Bellaire out to Katy and up to The Woodlands, answers to local building codes and nothing more.
Knowing which side of that line a house falls on shapes the whole job, and any roofing company in Houston that works the wider metro has to plan for both. GreenLight Roofing runs its operation out of an office on West Sam Houston Parkway, brings close to two decades of insurance industry experience to storm claims, and backs its work with a five-year labor warranty, with financing available for families who never budgeted for a new roof this year.
Paperwork Shows Up Before the Shingles Do
On the coastal side, a reroof is a regulated event. Most roof replacements, major repairs and alterations in the catastrophe area need an inspection and a certificate of compliance through the Texas Department of Insurance windstorm program. That certificate, the WPI-8, is what keeps a home eligible for wind and hail coverage through the Texas Windstorm Insurance Association, the insurer of last resort for many coastal owners who can’t find private wind coverage. Small patches under 100 square feet that don’t touch the decking are usually exempt.
The catch is timing. Inspections happen while the work is underway, by TDI staff or an appointed engineer, so a missing certificate is hard to fix once the shingles are down. After Hurricane Beryl, plenty of hurried replacements along the coast skipped this step, and owners found out later when they tried to sell or file a claim.
Inland, the paper trail looks different. Permit rules vary between the City of Houston and unincorporated parts of the county, and master-planned communities like The Woodlands, Cinco Ranch and Bridgeland often require architectural review before a new color or material goes up. The documents that matter most west of 146 tend to be the insurance claim file, the before and after photos, and the manufacturer warranty registration.
Nails, Decking and the Parts Nobody Sees
Coastal inspectors look under the surface. They check how the decking is fastened, what underlayment went down, how the valleys are lined, and whether shingles are installed to the wind-rated pattern. Roof vents, turbines and skylights need approved products too.
Inland roofs aren’t held to that layer of scrutiny, so quality comes down to the crew. That doesn’t mean the coastal standard is out of reach. A homeowner in Spring or Katy can ask for the same upgrades on a reroof, and several cost little when the deck is already exposed.
- Ring-shank nails for the decking, which grip far better than smooth nails when wind tries to lift a sheet.
- Six nails per shingle instead of four, placed in the manufacturer’s nailing strip.
- Starter strips with sealant along the rakes as well as the eaves, since wind usually peels a roof from its edges.
- Sealed seams on the roof deck, so water stays out even if shingles go missing in a storm.
- Drip edge fastened at tighter spacing around the perimeter.
Salt Air Rewrites the Metal
Close to Galveston Bay, the humid air carries salt, and salt is hard on anything metal. Drip edge, step flashing, vent collars, pipe boots and exposed fasteners can corrode years ahead of the shingles around them. Coastal crews lean toward aluminum, stainless or heavily galvanized components, and many owners schedule flashing checks on a shorter cycle than their inland relatives would.
Farther inland, metal lasts longer, and the enemies change. Summer heat bakes shingles, and the tall pines across Spring, Tomball and The Woodlands drop needles that pack into valleys and gutters, holding moisture against the roof. A roof in those neighborhoods often needs more cleaning than repairing.
Inland Storms Ignore the Map
It’s tempting to assume the wind rules exist because only the coast sees serious wind. Recent seasons argue otherwise. The May 2024 derecho threw gusts near 100 miles per hour across downtown and the western suburbs, and Beryl stripped shingles well into northwest Harris County a couple of months later. Hail adds another layer, with suburbs north and west of the city taking regular hits through spring.
That has pushed more inland owners to borrow coastal habits by choice. Class 4 impact-resistant shingles are one option, and Texas law requires insurers to offer a premium discount for qualifying impact-resistant roofs, so the upgrade can partly pay for itself. The FORTIFIED Roof standard from the Insurance Institute for Business and Home Safety goes further, combining sealed decking, enhanced nailing and stronger edges with an independent evaluation.
When One Family Owns Both Sides
Plenty of Houston households end up living on both sides of the line, with a main home in the suburbs and a weekend place near Kemah or La Porte, or a move from Katy to the bay after retirement. The same family can get two very different roofing experiences in a single year.
A few habits help. Before buying anything east of 146, search the TDI database for the home’s WPI-8 history. Before signing a coastal reroof contract, ask who files the inspection paperwork and when inspectors will visit. And before replacing an inland roof, decide whether coastal-style fastening is worth adding, since the deck will never be easier to reach than on replacement day.
Two houses can wear the same shingles and still be very different roofs. The difference lives in nails, edges, metal and paperwork, and in Houston, a highway decides which set of rules comes first.